Household Devices sector overview
What are Household Devices projects?
Household Devices is one of six sector groups within BeZero's sector classification system. Its projects are split among two sectors and five sub-sectors (see Figure 1).
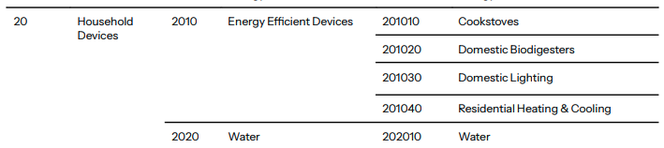
Figure 1. The breakdown of the Household Devices sector group. For more on BeZero Carbon’s Sector Classification system, click here.
Household Devices projects issue avoidance credits by reducing emissions from the combustion of polluting fuels relative to a baseline scenario, primarily through the introduction of cleaner or more efficient technologies for domestic use. Projects in the Energy Efficient Devices sector develop and distribute efficient technologies that displace higher-emission household equipment, while Water projects aim to improve water access, usage, and/or sanitation, whether through technologies such as filters or infrastructure such as boreholes and desalination plants.
Within the Cookstoves sub-sector, BeZero applies two additional qualifiers to support project labelling: Improved Efficiency and Fuel Switch. Improved Efficiency projects retain the baseline fuel but improve the cooking device's efficiency, meaning less fuel is required in the project scenario. Fuel Switch projects replace the baseline technology and fuel with a cleaner alternative, such as bioethanol, electricity from renewable sources, liquefied petroleum gas (LPG), or solar cookers. These two categories tend to face different barriers to adoption and distinct additionality and carbon accounting considerations.
Map of project and/or credit distribution
As of 10 September 2026, BeZero's sector-classified database recorded 2,121 Household Devices projects spread across 71 countries. India hosts the largest number of projects, at 335, followed by Uganda (180), Kenya (178), China (147), and Rwanda (144); Bangladesh, Malawi, Nepal, Burkina Faso, and Nigeria each also host more than 70 projects (see Figure 2).
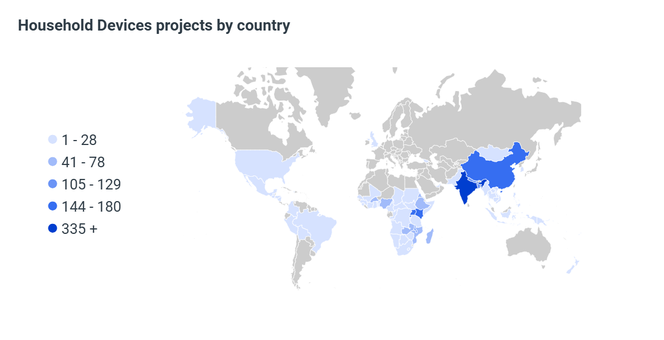
Figure 2. Map of Household Devices projects by country, as of 10 September 2026.
The number of projects in a country does not necessarily correspond with the volume of credits available there. Kenya holds the largest volume of available Household Devices credits, at approximately 29.0 million, followed by Rwanda (14.5 million) and India and Viet Nam (13.7 million each). Nigeria, Uganda, China, and Malawi each hold available credit volumes of over 12 million (see Figure 3). Across all countries in this dataset, available Household Devices credits total approximately 195.9 million.
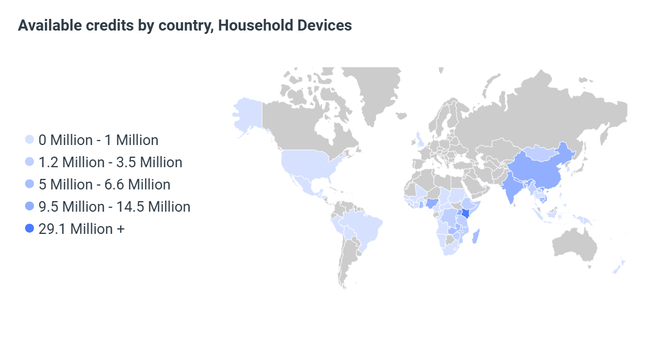
Figure 3. Map of the distribution of available credits in the Household Devices sector group, as of 10 September 2026.
Household Devices credit quality
BeZero has rated 134 Household Devices credits on an ex post basis (as of 10 September 2026). The distribution of headline ratings for Household Devices projects is similar to that of all rated ex post projects, although so far no project in the sector group has been rated above ‘A’ (see Figure 4).
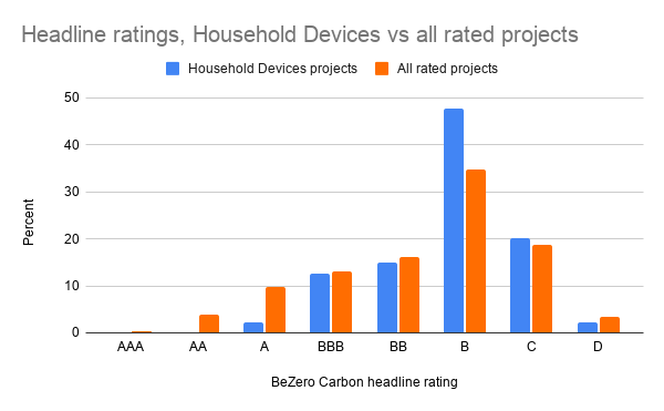
Figure 4. Distribution of headline ratings for Household Devices projects compared to all rated ex post projects, as of 10 September 2026.
The cluster of Household Devices ratings at ‘B’ belies a divergence across the underlying risk factor scores.
Additionality scores group toward the higher end of the scale, with a majority of projects scoring 'a' or above (see Figure 5).
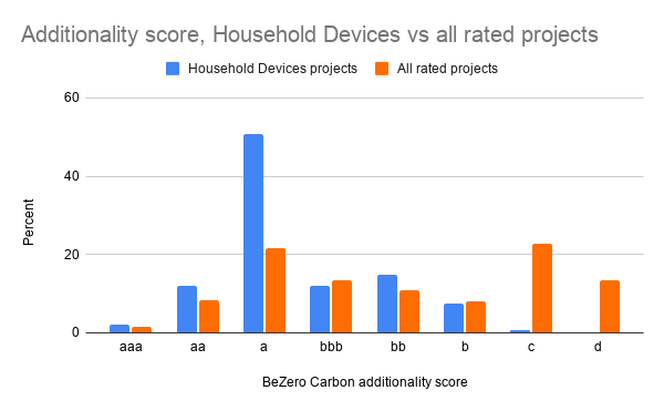
Figure 5. Distribution of additionality scores for Household Devices projects compared to all rated ex post projects, as of 10 September 2026.
Carbon accounting scores sit at the opposite end, with more than three-quarters of projects scoring ‘c’ or 'd’, indicating a ‘very low’ or ‘the lowest’ likelihood of accurate carbon accounting (see Figure 6).
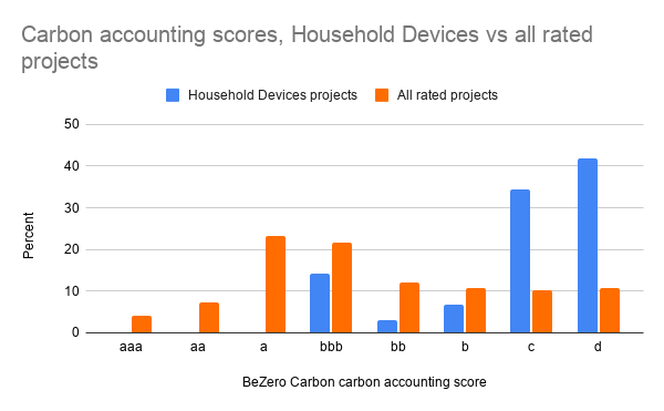
Figure 6. Distribution of carbon accounting scores for Household Devices projects compared to all rated ex post projects, as of 10 September 2026.
Permanence scores, by contrast, are uniformly strong: all the rated projects in the sector group score ‘a’ or above (see Figure 7, and read below for more details).
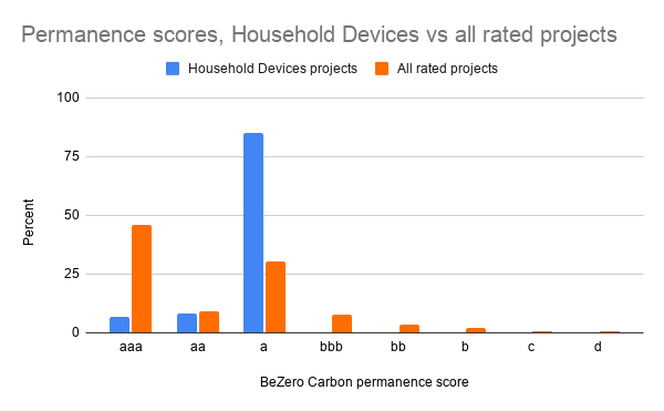
Figure 7. Distribution of permanence scores for Household Devices projects compared to all rated ex post projects, as of 10 September 2026.
What are the common risks of Household Devices projects?
Household Devices additionality risk
BeZero's assessment of additionality for Household Devices projects considers whether a significant share of the target population already had access to the project device, or a similar alternative, and whether historic trends suggest that end users might have transitioned to cleaner cooking practices or other clean fuels regardless of the project.
Where a population already shows high and increasing reliance on improved cookstoves or clean fuels such as LPG or electricity, additionality risk tends to be higher, as this indicates the project intervention may not have been necessary to achieve the desired outcome. Location also matters: rural areas, where carbon finance may be the only viable financing option and self-sustaining markets are less developed, tend to carry lower additionality risk than urban areas, where income, education, and existing infrastructure are more likely to support adoption independent of carbon finance.
Financial and barrier analysis form a second pillar of the additionality assessment. This considers whether project devices are too expensive for the target population without carbon finance, and whether carbon revenues have been used transparently to overcome financial, operational, social, or technical barriers to adoption. A lack of publicly available information on who receives project devices, or on how carbon finance is allocated, tends to increase uncertainty around a project's true additionality. Projects that sell devices at full retail price without subsidy, or that do not disclose an investment case for carbon finance - in other words, those that operate too much like a conventional business - are likely to face doubts as to whether carbon finance was necessary for implementation.
Legal and policy considerations also factor into additionality risk. Supportive government schemes, effective policy implementation, and clean energy policies that promote or mandate similar activities can all suggest that project outcomes might have occurred in the absence of carbon finance. Conversely, projects operating where government effectiveness is low, or in the absence of comparable policy support, tend to carry lower additionality risk.
Household Devices carbon accounting risk
Carbon accounting risk in Household Devices projects is heavily influenced by the robustness of baseline and project monitoring methods. Baseline fuel consumption is often uncertain, in part because monitoring approaches lack sufficient stratification, so household characteristics such as size, income, and access to fuel may not be adequately captured, leaving the data unrepresentative of the wider project population. Similar sampling risks apply to project-scenario monitoring, including fuel consumption, usage rates, and stove-stacking. The average reported usage rate across BeZero-rated cookstove projects is 89%, despite monitoring frequently covering only a small fraction of the stoves distributed. For Water projects specifically, the treatment of suppressed demand is a further material risk, since it allows projects to claim emission reductions for households that would not, in the baseline scenario, have used the relevant practice at all.
GHG conversion factors present a further source of risk. The fraction of non-renewable biomass (fNRB) used to determine the proportion of avoided emissions attributable to non-renewable wood harvesting remains high for many Household Devices projects, even where the CDM's TOOL30 (that uses outdated and temporally and spatially static data) is used to calculate it, and legacy projects that continue to rely on now-expired national default values carry particular risk.
Market leakage — where fuel saved by a project is absorbed by unmet demand elsewhere — is a material concern for commodity-driven project types such as those using charcoal or fossil fuels, even though this risk is virtually impossible to monitor directly.
Household Devices permanence risk
Permanence risk in Household Devices projects is generally assessed as low, reflecting the nature of the sector's carbon stock and reversal risk. Because Household Devices projects rarely disclose the exact location of fuelwood collection sites, and often have very large project areas — over half of BeZero-rated cookstove projects count an entire country as their operating area — it is usually not possible to definitively identify which forest areas are being sourced for biomass fuel, or which trees are being preserved as a result of project activities. This contrasts with nature-based solutions projects, where project boundaries are clearly defined and reversals can be monitored directly. While BeZero acknowledges the potential for reversal risk within the sector group, this lack of granular data means reversal risk is generally judged to be low.
What are the Beyond Carbon risks for Household Devices projects?
Our Beyond Carbon Risk Assessment evaluates the residual risk a project poses to people and the environment, separately from its carbon efficacy, across three risk factors: socioeconomic, environmental, and public sentiment. Each of these risk factors is assessed against a five-tier scale from lowest to highest residual risk. The assessment accounts for a project's inherent risk as well as any safeguards it has put in place to mitigate that risk, and is designed to be applied consistently across all project types and sectors.
Beyond Carbon risks are generally low for Household Devices projects, based on BeZero's ratings experience within the sector group to date.
Are Household Devices credits eligible for CORSIA and CCP?
Household Devices credits, and Cookstoves credits in particular, are eligible for use under both CORSIA and the Integrity Council for the Voluntary Carbon Market's (ICVCM) Core Carbon Principles (CCP) label. Several Cookstoves methodologies have been formally approved as CCP-eligible to date:
Gold Standard's methodology for Metered and Measured Energy Cooking Devices (versions 1.0-1.2)
Gold Standard's Technologies and Practices to Displace Decentralised Thermal Energy Consumption methodology (TPDDTEC, versions 2.0-3.1 and 4.0)
Verra's VM0050 Energy Efficiency and Fuel-Switch Measures in Cookstoves methodology (version 1.0).
Cookstove credits have also come to occupy an outsized position within CORSIA, the aviation sector's compliance offsetting scheme established by the International Civil Aviation Organization. According to a May 2026 market update from MSCI Carbon Markets, of the 43 projects that had at that point secured full eligibility for CORSIA's first phase, 40 were Cookstoves projects, based in countries such as Rwanda, Malawi, and Cambodia.
CORSIA's compliance requirements are also due to change materially from 1 January 2027, when its second phase becomes mandatory for participating states whose share of international aviation activity exceeds 0.5%, rather than voluntary as under the scheme's first phase. Given the scale of cookstove exposure within CORSIA to date, both this transition and any resulting changes to eligibility thresholds could have a material bearing on the demand for credits from the Household Devices sector.
Household Devices project methodologies
Household Devices projects apply a wide range of methodologies, reflecting the diversity of technologies and fuel types across the sector group. As of September 2026, BeZero's sector-classified database showed at least 39 distinct methodologies in use across Household Devices projects, whether applied individually or in combination with others. The most frequently applied methodology is Gold Standard's TPDDTEC, used by 714 of the sector group's 2,121 classified projects — around a third of the total. CDM's AMS-II.G. (464 projects) and Gold Standard's Simplified Methodology for Clean and Efficient Cookstoves (306 projects) are the next most common, followed by Gold Standard's methodology for emission reductions from safe drinking water supply (114 projects) and VMR0006 (112 projects).
Methodologies differ meaningfully in the rigour of the monitoring they require, which in turn affects the robustness of the usage and stove-stacking assumptions underpinning emission-reduction calculations. TPDDTEC and the Simplified methodology, for example, mandate kitchen observation, interviews with the primary cook, photographs of the cooking area, and GPS coordinates. By contrast, other widely used methodologies, including VMR0006 and CDM's AMS-II.G., require only a single question to establish whether a stove remains in use.
What's next for Household Devices projects
Several Household Devices methodologies have recently been introduced or updated with the aim of aligning more closely with CCP requirements, including VM0050 and updated versions of the RECH and MECD methodologies (RECH v5 and MECD v2). A new methodology designed for projects operating within the Paris Agreement Crediting Mechanism is reportedly in a draft phase and expected to be finalised soon. The Clean Cooking Alliance has led the development of the CLEAR methodology, which is also intended for projects aiming to operate in Article 6 markets. These developments point towards a sector that is gradually aligning its methodologies more closely with the market's highest integrity benchmarks.
Are you developing, investing in, or purchasing credits in the Household Devices sector? Get in touch to learn how BeZero’s ratings and assessments can help you make informed decisions.